By Kevin V. NguyenBusiness Reporter
Published
Seven Equity Group, which specializes in repositioning distressed retail, has reportedly been selected to purchase the vacant San Francisco Centre.

A New York group with expertise in redeveloping retail properties have been awarded the opportunity to buy and transform the San Francisco Centre Mall.
The group’s bid was selected from a pool of buyers this week after a competitive auction drew submissions from a swath of parties, including those that pitched a sports entertainment complex. Sources say a concept pitching a variation of a data center was never seriously considered.
The identity of the winning bid was reported by The Chronicle (opens in new tab) to be Seven Equity Group.
The firm will now have to close the deal with the current owners of the mall — a collection of bondholders that previously purchased the debt position from lenders Deutsche Bank AG and JPMorgan Chase Bank, who originated a $558 million mortgage to Unibail-Rodamco-Westfield and Brookfield Properties in 2016.
Westfield and Brookfield — who had owned and operated the mall for decades — walked away from the 1.2-million-square-feet property during the pandemic and defaulted on their debt last year, leading it to be foreclosed upon by the bondholders.


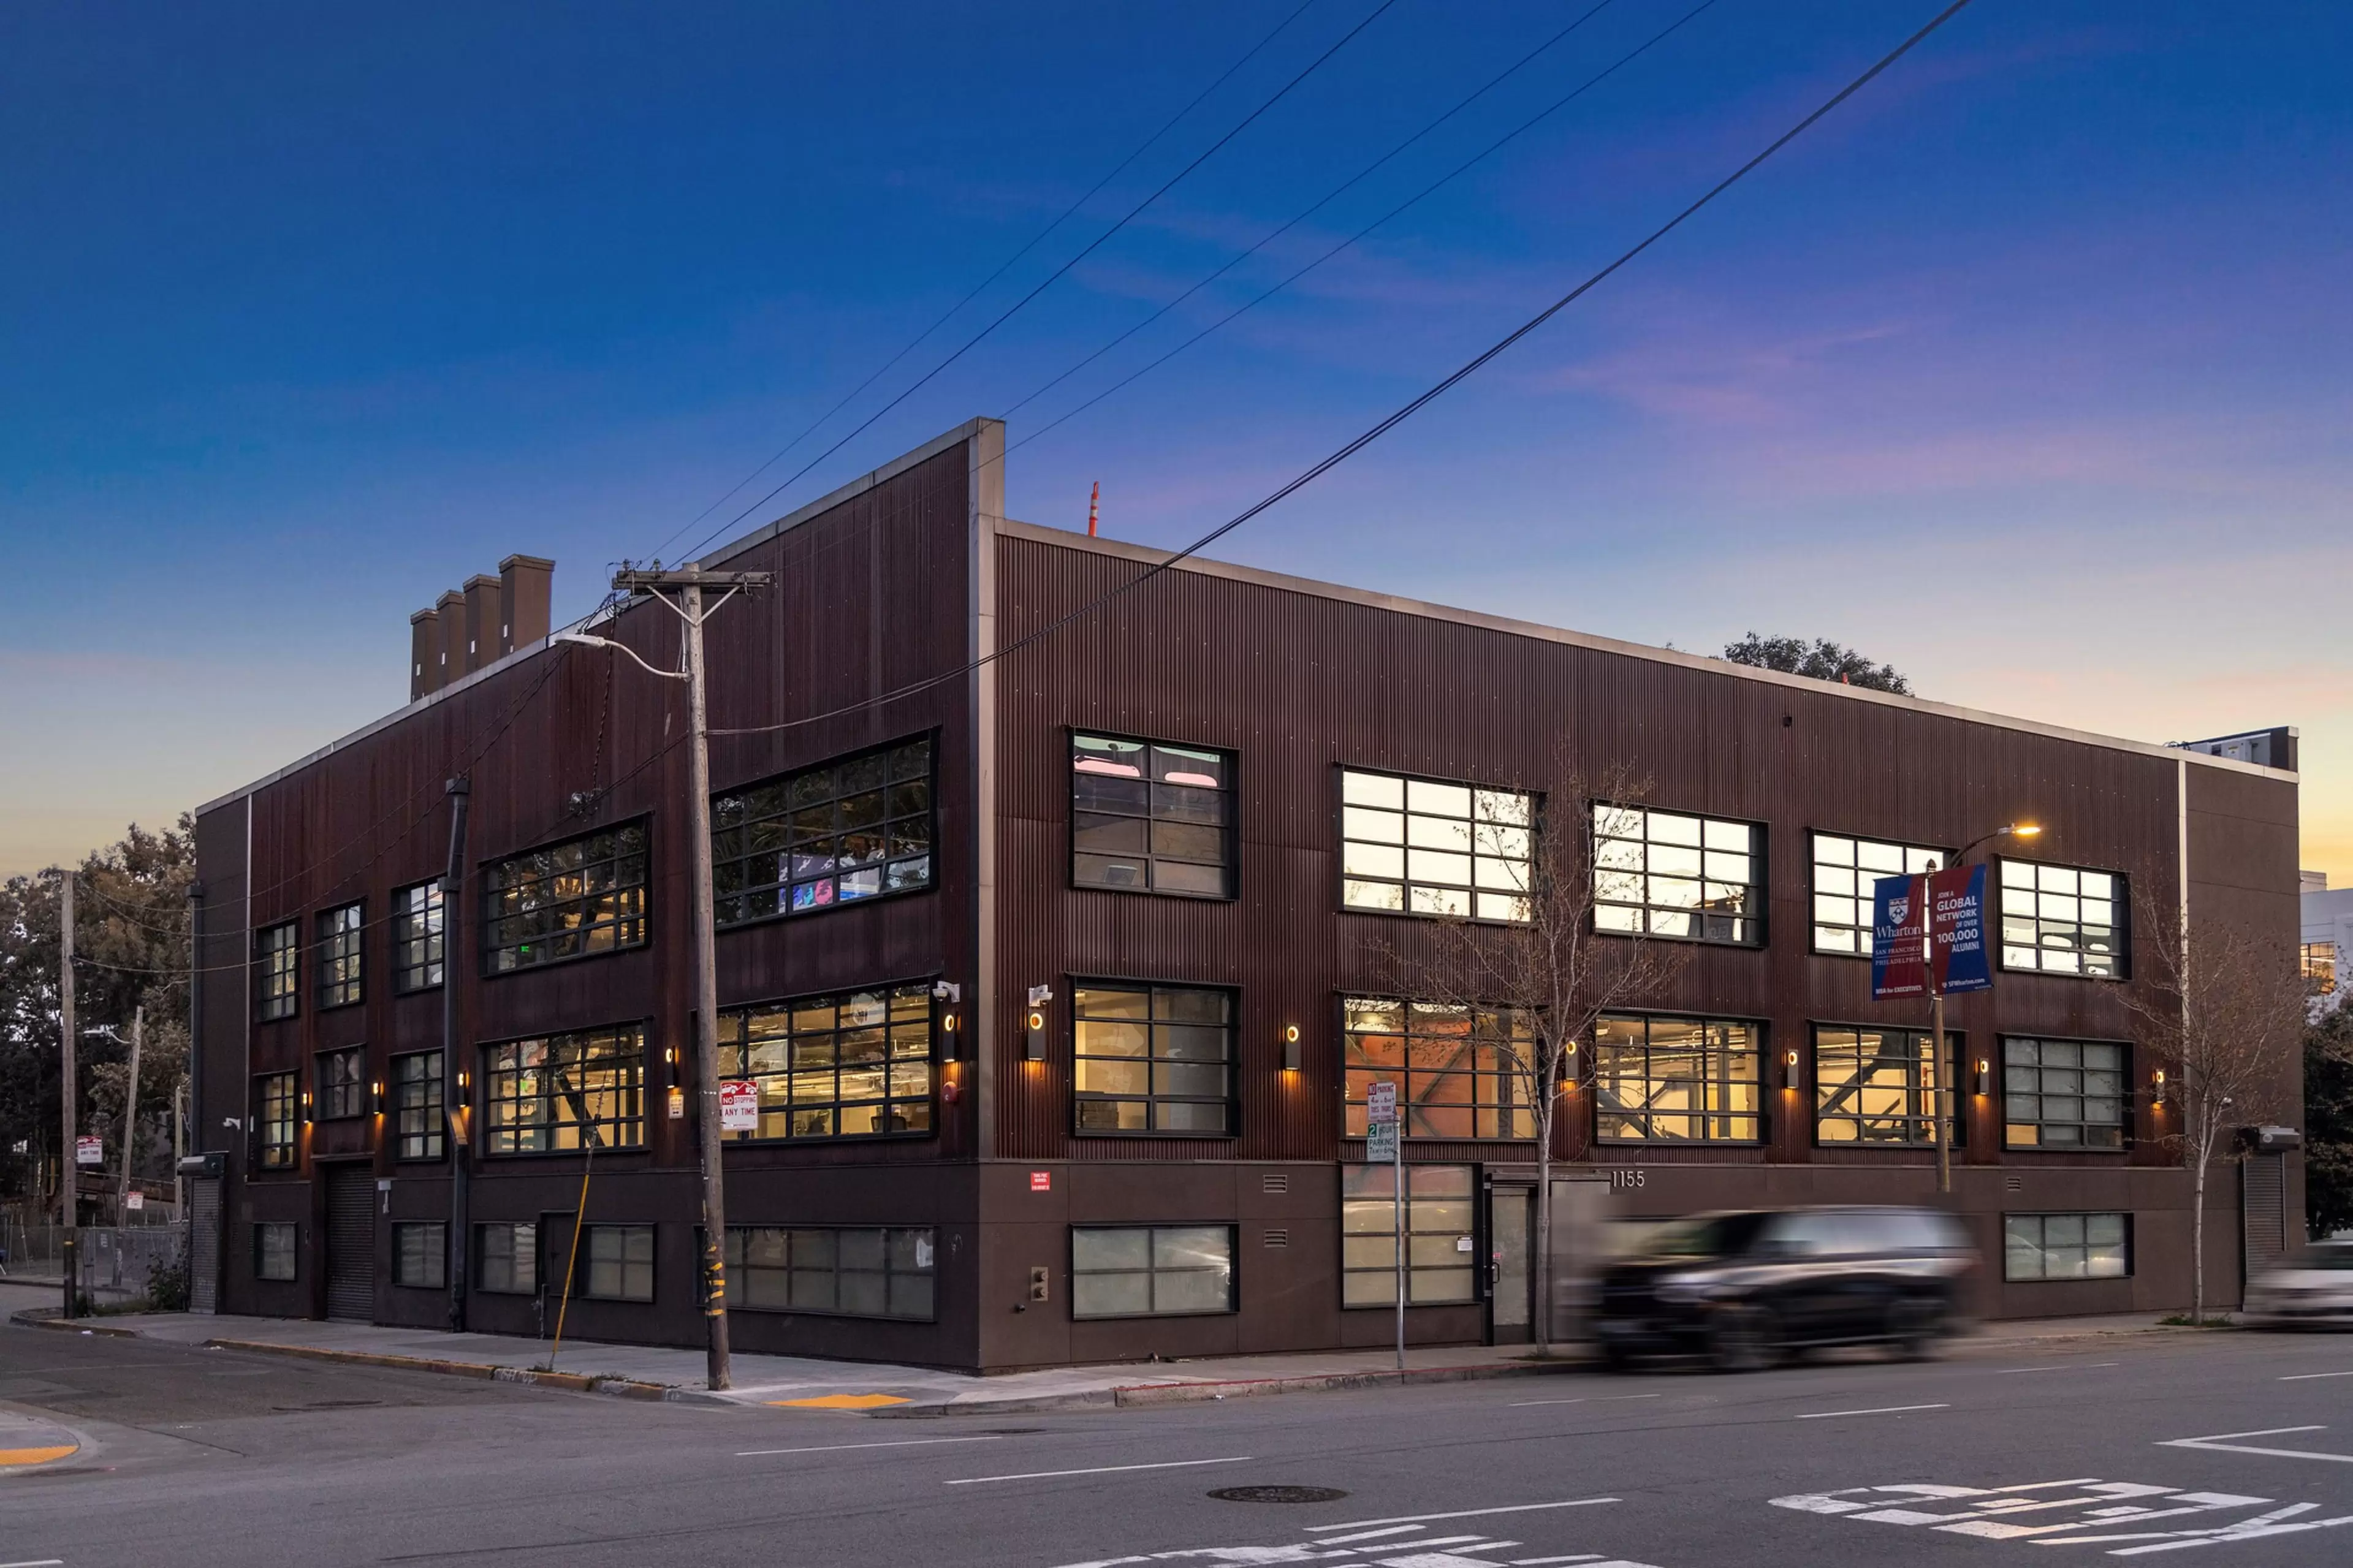
Seven Equity declined to comment when reached by phone. CBRE, which oversaw the auction, declined to comment.
Sources familiar with the bid process said the vacant mall is valued at around $130 million. The buyer would have to finance and pay that amount plus hundreds of millions more in redevelopment costs.
The mall was initially auctioned to a local partnership of Presidio Bay and Prado Group in March, but the two developers walked away from the deal after months of negotiations with the bondholders and San Francisco Unified School District hit an impasse.
The school district owns roughly 75,000 square feet of land beneath the property and leases it to whoever owns the mall. That long-term arrangement — which generates low seven-figures in recurring revenue for the city — was extended from 2043 to 2082 after Presidio Bay and Prado pulled out of the deal.
Seven Equity, led by former Wells Fargo executive Ray Falack, focuses on assets valued between $50 to $150 million, according to its website. The firm in July purchased another San Francisco property, located at 25 Taylor St., which is connected to the Golden Gate Theater. Last month, it bought two side-by-side Mission Street buildings near the mall from Westfield for $15.5 million.
Reviving the albatross mall would be a pivotal step in turning around one of the most important stretches of downtown San Francisco which was hollowed out during the pandemic.
City officials and neighbors have likened the drawn-out death of the mall — which is connected to BART and straddles Union Square — to that of a black hole for the neighborhood.
“We want to see a strong vision for a mixed‑use development that is active, vibrant, and serves as a regional destination, one that advances our vision for a 24/7 downtown,” Anne Taupier, executive director of the Office of Economic and Workforce Development, previously told The Standard.
More about the author
Kevin V. Nguyen is a business reporter at The Standard. He previously covered commercial real estate at The Silicon Valley Business Journal and got his first journalism break at The Sacramento Bee.